TL;DR
- Financing a poultry farm is not the same as financing a regular house, and lenders treat it differently.
- USDA FSA loans are the most common path for both new and existing growers, with two main types: Direct and Guaranteed.
- Down payment requirements, interest rates, and approval timelines vary a lot depending on the loan type and your experience level.
- Seller financing and conventional ag loans exist too, but each comes with its own tradeoffs.
- Get pre-qualified before you fall in love with a listing. It saves everyone time.
If you are trying to figure out how to finance a poultry farm, you are probably staring at a listing right now wondering how the math works. I get this question more than almost any other, so let’s walk through it properly.
Why poultry farm financing is different
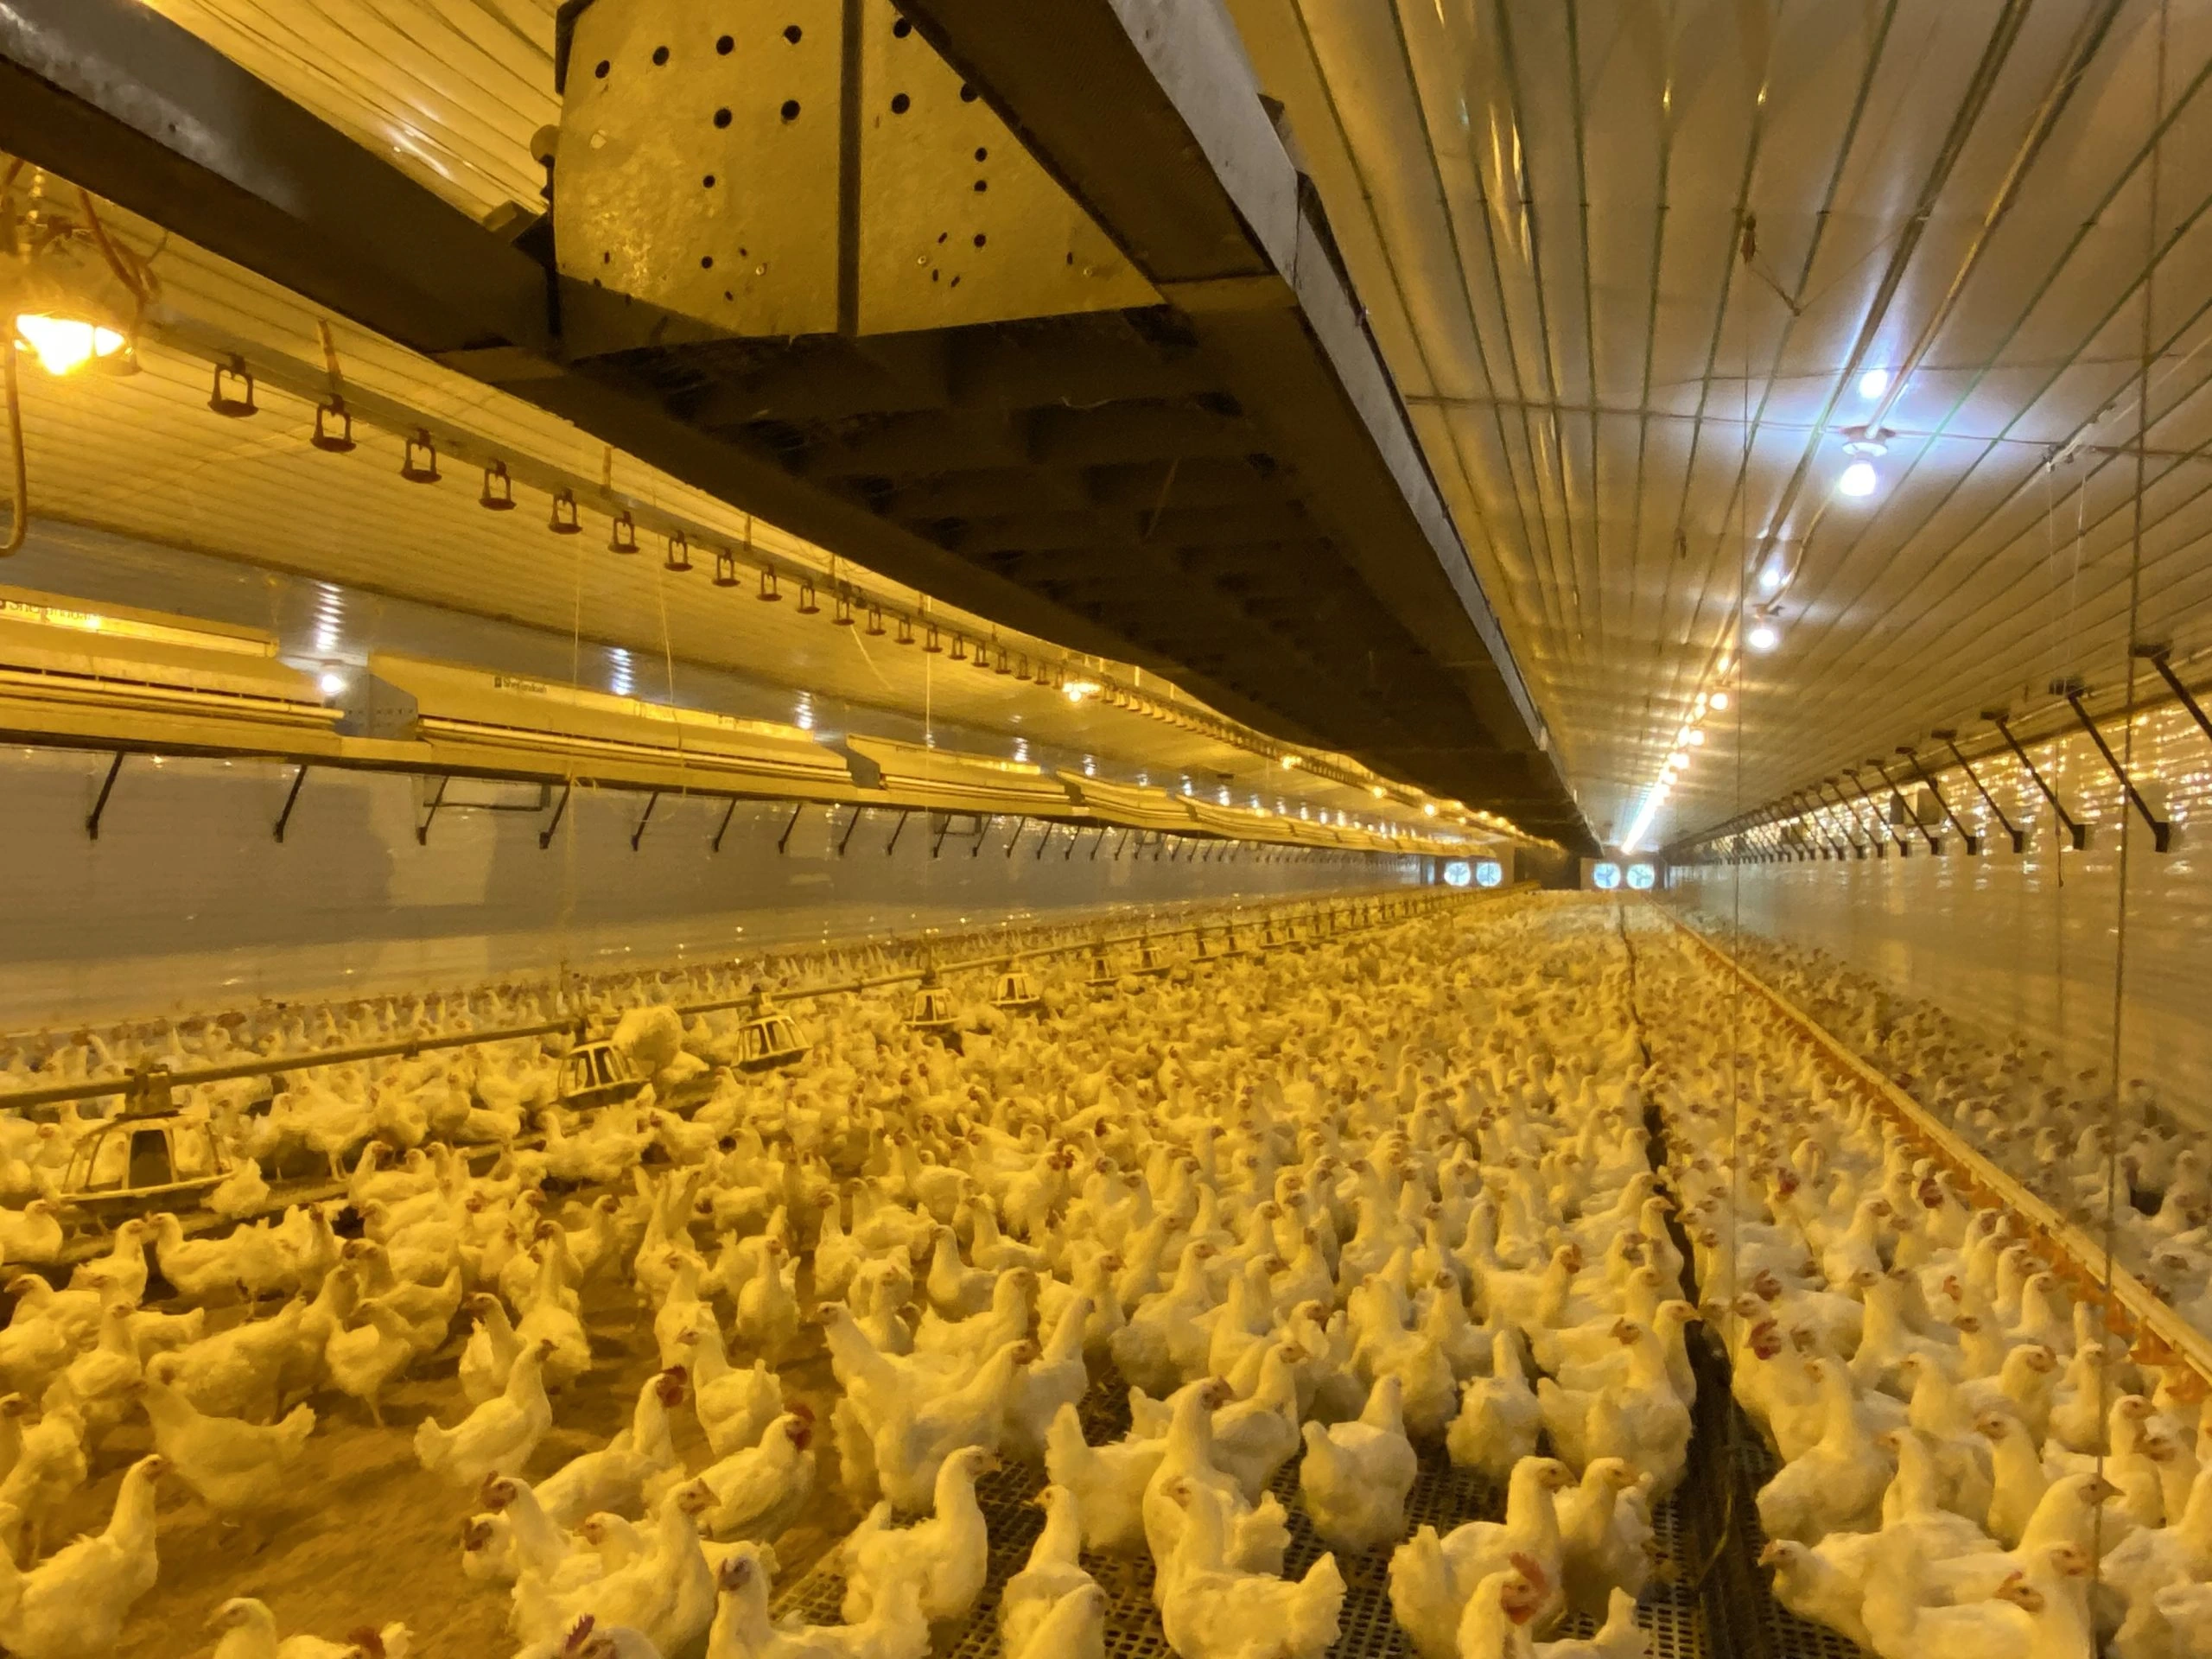
A regular home loan looks at your income, your credit, and the value of the house. A poultry farm loan looks at all of that, plus the land, the houses, the equipment inside those houses, and whether there is an active integrator contract attached to the property.
That last part matters more than most first-time buyers expect. A lender wants to know if the farm can generate income once you own it, not just what it’s worth on paper.
Daniel, my husband, put it well one evening when I was working through a listing. He said financing a poultry farm is closer to financing a small factory that happens to sit on dirt. I laughed, but he wasn’t wrong.
USDA Farm Service Agency loans
Most poultry farm buyers end up looking at USDA FSA loans at some point. There are two main types, and they work differently.
FSA Direct Farm Ownership Loans come straight from the USDA. These are aimed at family farmers, including first-time buyers, and often have lower down payment requirements than a conventional loan. The tradeoff is a longer application process, since the USDA underwrites the loan itself rather than a bank.
FSA Guaranteed Farm Loans work through a regular bank or ag lender, with the USDA guaranteeing a portion of the loan. This usually means faster processing than the Direct program, though the terms can vary more depending on which lender you use.
Both programs are designed with working farms in mind, not hobby properties. If a listing says “poultry farm” but has no active contract and no real production history, it may not qualify the same way.
What lenders want to see
Before you get too far into the shopping process, it helps to know what a lender is going to ask for. In my experience looking at these deals from the outside, the list usually includes:
- Farm financial history, if the operation is already active
- Copy of the current integrator contract, if one exists
- Age and condition of the poultry houses
- Equipment inventory, including generators and ventilation systems
- Buyer’s own credit and income documentation
- A realistic operating budget for the first year
That last one trips people up. A lender does not just want to know what the farm made last year. They want to know what you plan to do with it, and whether your numbers hold up.
Conventional agricultural loans
Some buyers go through a conventional ag lender instead of USDA. These lenders specialize in farm properties and sometimes move faster than USDA, but usually require a larger down payment and charge a higher interest rate.
This route can make sense if you have strong existing income, a solid credit profile, or you are expanding an operation you already run successfully. It tends to make less sense for a first-time buyer with limited capital.
Seller financing
Every so often, a seller is willing to finance part or all of the sale directly. This shows up more often on smaller family operations than on large commercial farms.
Seller financing can move quickly since there is no bank underwriting process. But it also means the terms are whatever you and the seller agree to, so you need to be careful. I always tell buyers to have a real estate attorney review any seller-financed agreement before signing anything.
Comparing your financing options
| Financing Type | Typical Down Payment | Speed | Best For | Watch Out For |
|---|---|---|---|---|
| FSA Direct Loan | Often lower, case by case | Slower, USDA underwrites directly | First-time buyers, family farms | Longer approval timeline |
| FSA Guaranteed Loan | Moderate, lender dependent | Faster than Direct | Buyers wanting bank speed with USDA backing | Terms vary by lender |
| Conventional Ag Loan | Higher, often 20-30% | Fastest of the three | Experienced growers, strong credit | Higher interest rate |
| Seller Financing | Negotiable | Fastest, no bank involved | Smaller family operations | Terms are only as good as the contract |
A quick word on gross income versus what the bank sees
I mentioned this in a few other places on the site, and I will keep saying it because it matters. A listing that says the farm generates $400,000 a year is talking about gross income, not profit.
A lender is going to want the real operating numbers. Feed costs, utilities, labor, equipment maintenance, and loan payments on any existing debt all come out of that gross figure before you see a dollar of it.
If you are looking at farms in a specific state, our Georgia poultry farm page and Texas poultry farm page both include current listings with pricing and acreage details, which is a good place to start pulling real numbers to bring to a lender.
Getting pre-qualified before you shop
I always recommend getting pre-qualified before you start seriously touring farms. It does two things. First, it tells you what price range makes sense for your situation. Second, it makes you a more credible buyer when you do find a farm you want.
Sellers and their agents pay attention to whether a buyer has financing lined up. It can be the difference between getting a serious look at a listing and getting passed over for someone who is ready to move.
Final thoughts from Rose
Buying a poultry farm is a big financial step, and the financing side is where a lot of that decision gets made. I am not a loan officer and I am not going to pretend to be one. What I can tell you is what I have seen work for other buyers, and where people tend to get stuck.
Talk to an FSA loan officer early, even before you have picked a specific farm. Bring your questions. Bring your numbers. And do not be shy about asking a seller for the real operating costs behind their asking price.
Frequently Asked Questions
Do I need farming experience to qualify for a USDA farm loan?
No, but it can affect your options. FSA Direct loans have programs specifically for beginning farmers, so a lack of experience does not automatically disqualify you.
How much down payment do I actually need for a poultry farm?
It depends heavily on the loan type. USDA programs can require less than a conventional ag loan, which might ask for 20 to 30 percent down.
Can I use a USDA loan to buy a farm with an existing integrator contract?
Yes, and in many cases this makes the loan easier to approve, since it shows the property has an income history and an active buyer for the birds.
What happens if the integrator contract is not transferable?
This is something you need to check before you get too far into the process. Some contracts transfer with the sale, others require the new owner to reapply, and that can affect your financing timeline.
Is seller financing safer or riskier than a bank loan?
Neither is automatically safer. It depends entirely on the terms of the agreement, which is why I always recommend having an attorney review it before signing.